CXMT Becomes China's Most Valuable Company As UBS Calls Apple Sourcing Report A "Key Catalyst"
ChangXin Memory Technologies surged 12% to a record 61.80 yuan after reports that Apple is considering sourcing its memory chips, with UBS calling the report a “key catalyst.” The setup is most directly positive for CXMT, while Apple faces a sourcing-development read-through without a quantified impact on its earnings.
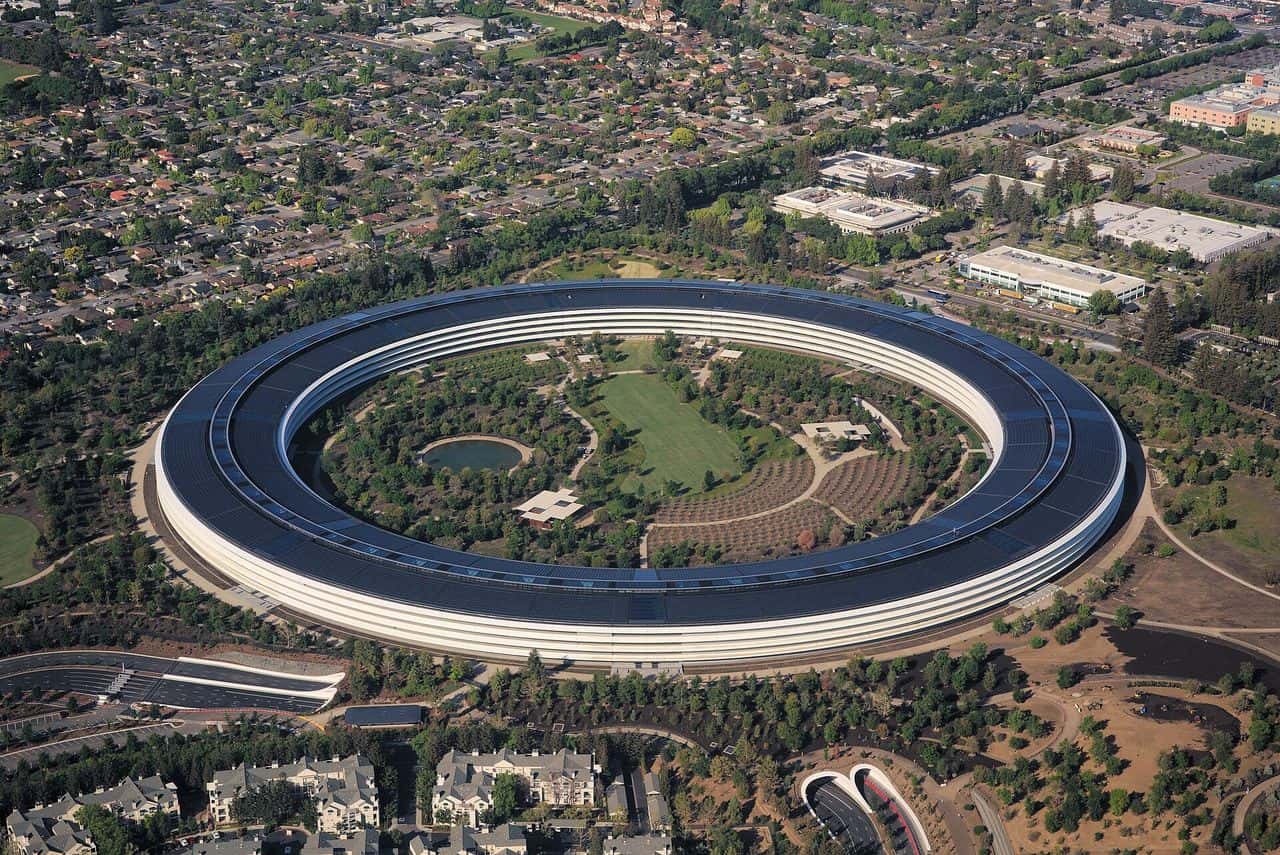 File photo · Apple Park, Cupertino · Apr 2018 · Daniel L. Lu (dllu) · CC BY-SA 4.0 · Source & license
ChangXin Memory Technologies rose 12% on Monday to 61.80 yuan, lifting its market capitalization to 4.13 trillion yuan. The move followed reports that Apple is considering using CXMT memory chips and came alongside broader strength in chip stocks after gains in SanDisk and Micron last week.
CXMT is described as China's top DRAM maker. UBS analyst Jason Milao covers CXMT with a Buy rating and a 70 yuan price target, and characterized the Apple sourcing report as a key catalyst.
For Apple, the relevant next evidence is confirmation of a supplier relationship and any effect on its sourcing mix, costs, or product qualification process; for CXMT, the focus is whether the reported opportunity becomes an order rather than remaining a market narrative.
The sourcing report is a clear catalyst for CXMT but only a mixed read for AAPL, where the commercial impact remains unquantified.
For AAPL, the immediate read is mixed because a potential new memory supplier could affect sourcing flexibility. Apple’s FY2025 revenue was $416.2B with 46.9% gross margins and 26.9% net margins, so the sourcing headline alone does not support a material earnings-direction call.
The trade read fails if Apple confirms CXMT as a qualified supplier with a clearly favorable cost or supply effect, or if the report is retracted and the relationship does not progress.
CoverageSource: ZeroHedge · Published here MON, AUG 17 · 7:45 AM ET · the only report in this recordHow this is decided →
Earlier context and later coverage are dated relative to this report. Automatically linked reports may cover a broader event.
No later reports linked yet.
Follow this story to find new evidence in your Following desk.
Price context does not establish that the story caused the move.
AAPL could benefit from greater memory-sourcing flexibility if CXMT is ultimately qualified, against a business already reporting $416.2B of revenue and 46.9% gross margins.
The immediate downside case is limited but concrete: an unconfirmed supplier report may have no earnings effect, while any sourcing shift that introduces qualification or supply-chain complexity would dilute the headline benefit.
Kept as written · your side, if you take one, is graded privately against licensed closes after 10 trading days · nothing here is advice · How the Wire is made →