U.S. diesel prices hit record high after attacks on Saudi pipelines
U.S. diesel prices reached a record high as attacks on Saudi pipelines intensified fears that Middle East fighting could disrupt oil supplies. The shock raises near-term fuel-cost and inflation risks, though the full duration and scale of any supply outage remains uncertain.
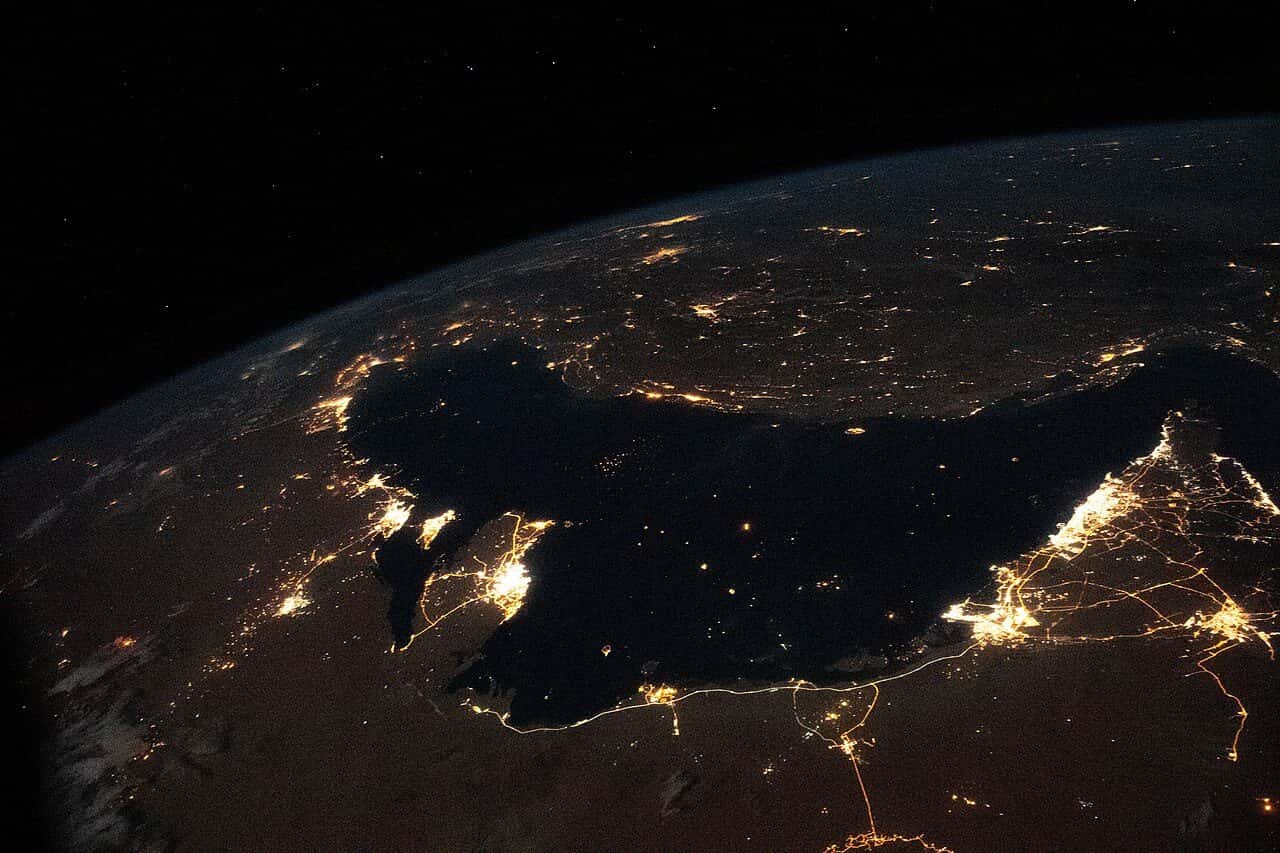 File photo · The Persian Gulf at night, from the International Space Station · Aug 2020 · NASA · Public domain · Source & license
The story
U.S. diesel fuel reached a new high as markets reacted to attacks on Saudi pipelines and growing concern that the conflict could threaten additional oil supplies. Key details about Saudi capacity offline, the duration of any disruption, and material changes to crude exports remain unclear.
The move adds an energy-supply shock to an already escalating Middle East conflict. Diesel prices are particularly sensitive to disruptions in crude and refined-product logistics, but the immediate market response alone does not show whether the event represents a temporary risk premium or a lasting change in supply conditions.
The direct exposure is broad rather than concentrated in a named company: refiners and fuel distributors face higher input and replacement costs, while producers could benefit from stronger oil prices if supply is actually curtailed. Transport, industrial and consumer businesses would face pressure from more expensive diesel, with the potential for the shock to feed into wider inflation.
Confirmation of lost barrels, the duration of the pipeline disruption and subsequent updates on exports and inventories will be decisive in understanding the impact. Monitoring the supply-risk premium is warranted as this situation develops.
Our read · Fri, Sep 11
The Saudi pipeline attacks lift the near-term energy and inflation risk premium, but the NYT report does not support a single-name equity read without a quantified supply outage.
Why. The immediate consequence is a higher fuel-cost and inflation-risk premium, while the trading implication remains two-sided because a confirmed supply loss could support producers but raise costs across fuel-intensive businesses. The absence of a quantified outage, named company exposure or forward event keeps this at a market-risk observation rather than a directional single-name Angle.
Both cases
What could change this view: The risk premium fades if pipeline operations and oil exports continue without a material interruption.
Who reported it · 4
Keep reading
Latest on the Wire
BlackRock bitcoin ETF posts $541.1 million outflow as tech sell-off spreadsAnthropic debut fails to halt technology-led slide in US stocksUS MATCH Act puts ASML at center of China chip export disputeBeijing plans to bar young red-chip firms from overseas listingsGerman producer prices jump 8.1% in October as industrial inflation acceleratesContinue on the Wire →Latest on the Wire
AMD shares fall 11% after Hunterbrook warns over China linksWalmart raises full-year outlook as e-commerce wins shoppersAnthropic IPO could become the largest in US history on ThursdayContinuing claims rise as Goldman sees Fed hikes in December and MarchContinue on the Wire →Top this week
Nvidia allies lobby board to bring back Jensen Huang as CEONvidia chair rules out Huang return as CEO after 75% sales outlookAnthropic Said to Guide IPO Pricing Above Market RangeNvidia interim CEO Colette Kress faces first earnings test after HuangBitcoin nears $64,000 as Anthropic IPO lifts Nasdaq futures nearly 2%About this report
Reported by NYT Business as Energy Markets Rattled After Saudi Pipeline Attacks
, . Who answers for this
4 reports from 4 publishers in this record. Closes are licensed end-of-day data from Databento; the move after a story is its first close against the close before it. How this is decided →
Kept as written · your side, if you take one, is graded privately against licensed closes after 10 trading days · nothing here is advice · How the Wire is made →