Nvidia invests $3.5 billion in MediaTek convertible bonds
Nvidia is investing $3.5 billion in MediaTek convertible bonds, extending its semiconductor ecosystem through a strategic financing. The deal creates a new capital and partnership link for NVDA, but the absence of transaction terms or an identified commercial commitment leaves the immediate earnings impact unclear.
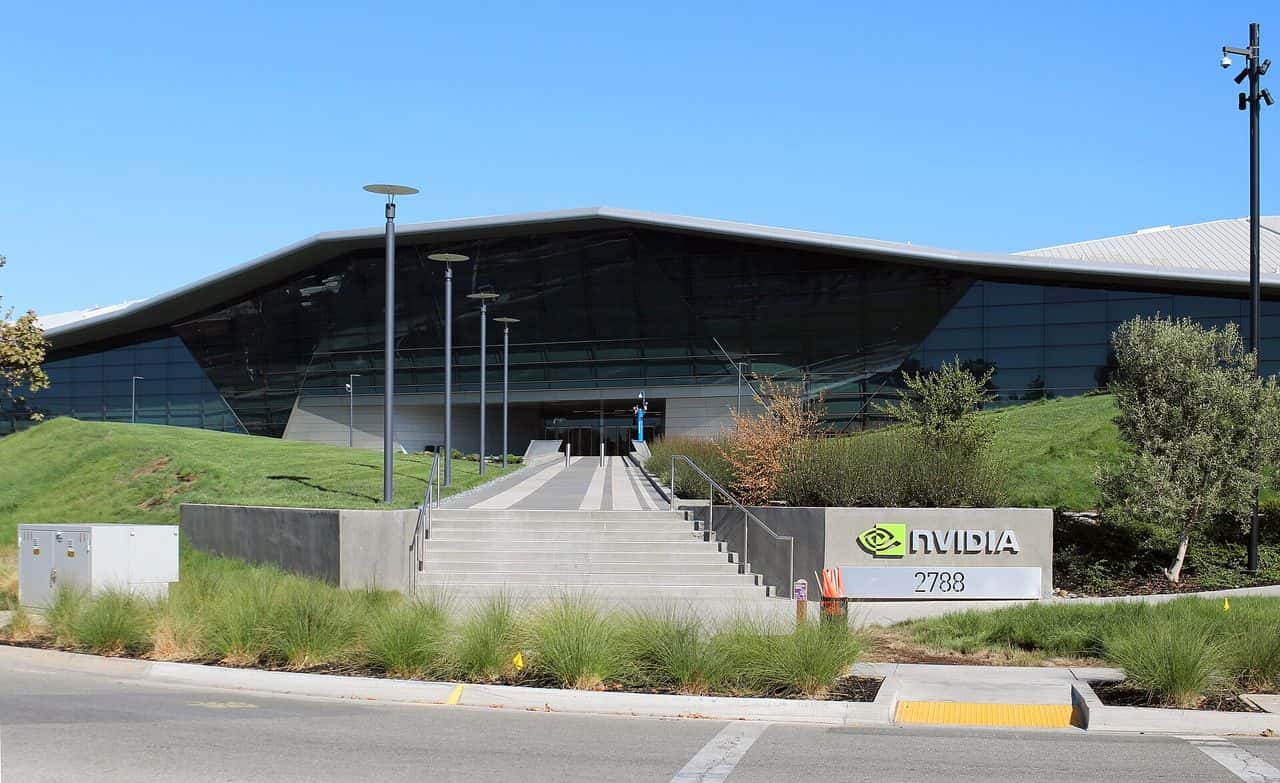 File photo · NVIDIA’s headquarters, Santa Clara · Aug 2018 · Coolcaesar · CC BY-SA 4.0 · Source & license
The transaction gives Nvidia exposure to MediaTek through $3.5 billion of convertible bonds, according to Investing.com on August 31. Those missing terms make it impossible to determine how much of the investment is financial exposure and how much is intended to deepen an operating relationship.
Nvidia enters the deal from a position of substantial scale. Its latest enrichment shows fiscal-year revenue of $215.9B, up 65.5% year over year, with a 71.1% gross margin and a 55.6% net margin. The investment therefore sits alongside a business generating significant cash and earnings power, rather than representing a capital commitment from a company whose core operations are under immediate financial strain.
For Nvidia, the direct connection is the convertible security and any strategic access it may provide to MediaTek. MediaTek is the issuer and would receive the capital, while Nvidia would hold an instrument that can potentially become equity under terms that were not disclosed in the supplied reporting.
The available report also leaves important questions unresolved. There is no opposing statement or management commentary in the supplied material, so the strategic rationale is reported but not independently established here.
The next useful disclosures are the bond terms, any regulatory or exchange filing that identifies the conversion mechanics, and comments from either company on the intended commercial relationship. Nvidia’s next earnings release would also show whether the investment affects cash, securities holdings, dilution, or guidance, although no date for that release was provided. Until those details emerge, the transaction is a notable ecosystem signal but not a quantified change to Nvidia’s operating outlook.
The MediaTek financing broadens Nvidia’s strategic semiconductor footprint, but undisclosed conversion terms and no stated revenue linkage leave the near-term read for NVDA mixed.
The immediate consequence is strategic optionality rather than a quantified earnings change: Nvidia is committing $3.5 billion to a convertible instrument while the supplied report gives no conversion terms or commercial agreement. Its $215.9B revenue base, 65.5% year-over-year growth and 55.6% net margin show capacity for the investment, but they do not establish incremental revenue or accretion from MediaTek.
The read is invalidated by disclosed terms showing material dilution, an unfavorable conversion valuation, or no meaningful operating relationship beyond a financial investment.
CoverageSource: Investing.com · Published here TUE, SEP 1 · 3:06 PM ET · 8 reports · 5 publishers in this record · latest listed: CNBC · TUE, SEP 1 · 3:06 PM ETHow this is decided →
- Bloomberg Television — Nvidia Investing $3.5 Billion in Chipmaker MediaTek
- Bloomberg Television — Nvidia Partnership With MediaTek Expands, Huang Says
- Bloomberg Television — Nvidia CEO Huang on the $3.5 Billion Deal With MediaTek
- Bloomberg Television — Nvidia to invest $3.5 billion in chipmaker MediaTek
- TechCrunch — Nvidia’s $3.5B MediaTek bet reveals its plan for tackling Big Tech’s AI chip buildout
- Yahoo Finance — Nvidia Slips As AI Circular Financing Fears Rise Amid $3.5 Billion Deal; Is Nvidia A Buy Now?
- CNBC — Qualcomm rival MediaTek jumps 10% after $3.5 billion Nvidia AI chip deal
Earlier context and later coverage are dated relative to this report. Automatically linked reports may cover a broader event.
No later reports linked yet.
Follow this story to find new evidence in your Following desk.
Price context does not establish that the story caused the move.
The strongest bull case is that the $3.5 billion convertible position secures strategic access to MediaTek while Nvidia’s $215.9B revenue and 55.6% net margin provide ample financial capacity.
The bear case is stronger on disclosure risk: without a conversion price, maturity, or identified revenue agreement, the transaction may add financial exposure without changing Nvidia’s operating trajectory.
Kept as written · your side, if you take one, is graded privately against licensed closes after 10 trading days · nothing here is advice · How the Wire is made →