Why the U.S. Treasury is buying back double the government bonds it normally does
The U.S. Treasury plans to buy back at least twice as many long-dated government bonds as usual, putting its debt-management strategy under scrutiny from bond investors and the Federal Reserve. The move creates a rates-sensitive policy setup in which Treasury’s attempt to improve market liquidity could instead sharpen tensions over long-term yields and monetary-policy independence.
The Treasury is preparing to expand its purchases of long-dated government bonds to at least double the volume it normally buys. The program is intended to reshape the government's outstanding debt profile and address trading conditions in older Treasury securities.
Treasury buybacks are designed to retire less-liquid or less-desired securities and can help make the broader government-bond market easier to trade. The latest plan comes with the long end of the Treasury market already carrying particular importance for borrowing costs and the government's financing strategy. Its scale makes the operation more consequential than a routine debt-management adjustment.
The principal actors are Treasury Secretary Scott Bessent, the bond market and the Federal Reserve. Treasury's purchases could affect the supply of long-dated bonds available to investors, while the resulting price and yield response would feed into borrowing conditions across markets. The Fed is relevant because long-term yields also transmit financial conditions, even though Treasury—not the central bank—would be conducting the buybacks.
The unresolved issue is how bond investors interpret the purchases: as a technical effort to improve liquidity, or as a policy intervention with implications for the supply and pricing of government debt. There is potential tension between the Treasury secretary, bond markets and the Fed, rather than a settled conflict.
Market reaction in long-dated Treasury yields and auction demand will show whether investors view the program as supportive or disruptive. Statements from Bessent and Federal Reserve officials should clarify how the debt-management plan is being separated from monetary policy. Whether the purchases materially change the supply of long-dated bonds, whether liquidity improves in the targeted securities and whether the Fed sees any effect on the financial conditions it is trying to manage remain open questions.
The Treasury buyback plan puts long-end rates and policy coordination in play, but the reporting does not support a single-name equity read.
The immediate implication is a policy-and-rates question, not a company-specific earnings or cash-flow signal. The read will turn on the buyback’s operational details and whether long-dated bond yields and liquidity respond as Treasury intends without creating visible friction with the Federal Reserve.
The trade thesis is invalidated if Treasury’s final terms are small, routine or produce no meaningful reaction in long-dated bond yields or market liquidity.
CoverageSource: NPR · Published here THU, SEP 3 · 4:41 PM ET · the only report in this recordHow this is decided →
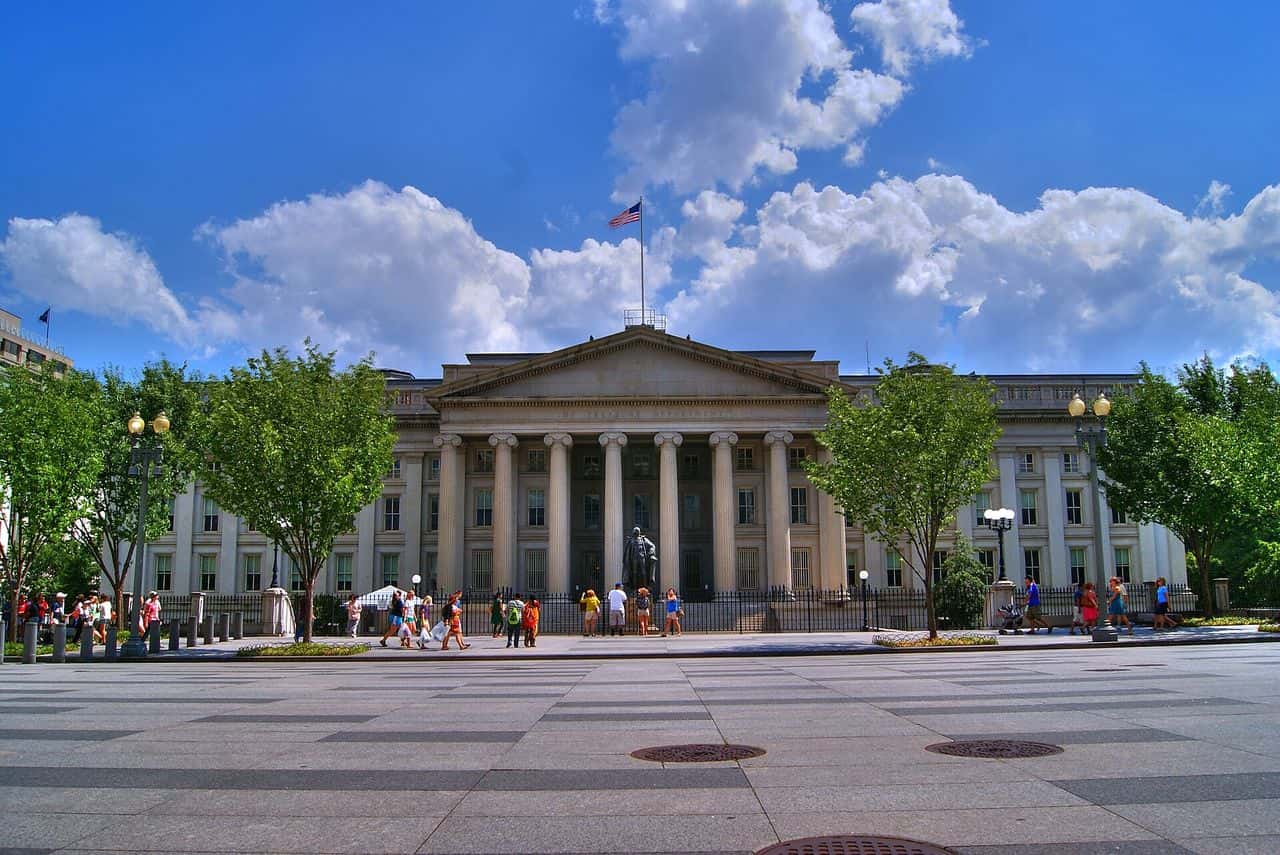 File photo · The US Treasury Building, Washington · Jun 2012 · Erich Robert Joli Weber · CC BY-SA 3.0 · Source & license
Earlier context and later coverage are dated relative to this report. Automatically linked reports may cover a broader event.
No later reports linked yet.
Follow this story to find new evidence in your Following desk.
Treasury’s larger buybacks could improve liquidity in older long-dated securities and reduce the market impact of a substantial outstanding bond supply.
The opposing case is that the buyback plan lacks sufficient specificity around size, timing and market reaction to establish a durable rates direction.
Kept as written · your side, if you take one, is graded privately against licensed closes after 10 trading days · nothing here is advice · How the Wire is made →