Key Events This Week: FOMC Minutes, PMIs, Industrial Data; WalMart And Home Depot Earnings
This week’s catalysts include FOMC minutes, PMI and industrial data, alongside earnings from Walmart and Home Depot, as higher oil prices, fiscal deficits and AI-related capital demand push longer-term Treasury yields higher. That rates backdrop raises the bar for rate-sensitive retailers such as Home Depot even as its earnings provide a company-specific catalyst.
The week’s calendar brings the release of the FOMC minutes, purchasing-managers surveys, industrial data and quarterly results from Walmart and Home Depot. Deutsche Bank’s Peter Sidorov said expectations for an imminent Federal Reserve rate hike have receded, but the shift has coincided with a significant steepening of the US yield curve and a sell-off in longer-dated bonds.
The report attributes upward pressure on yields to higher oil prices, elevated fiscal deficits and demand for capital from the AI investment boom. Home Depot is the named equity in play; Finnhub’s enrichment shows FY2026 revenue of $164.7B, up 3.2% year over year, with a 33.3% gross margin, an 8.6% net margin and diluted EPS of $14.23.
The immediate read will depend on the FOMC minutes, the incoming activity data and Home Depot’s earnings. Key follow-through items are the direction of long-end yields, the company’s sales and margin commentary, and whether the macro data reinforces or relieves pressure on rate-sensitive consumer demand.
The week’s rates and macro catalysts leave HD with a mixed setup: its $164.7B revenue base and 3.2% growth support the earnings case, but long-end yield pressure raises the hurdle for a stronger read-through.
The setup is balanced because Home Depot has a concrete operating base—$164.7B of revenue, 3.2% year-over-year growth and an 8.6% net margin—while the macro backdrop could weigh on housing-linked and discretionary demand. The decisive variable is the interaction between the FOMC minutes, long-end yields and Home Depot’s margin and demand commentary.
A renewed long-end Treasury sell-off or weaker consumer and housing demand would pressure the setup; stronger-than-expected Home Depot results and easing yields would invalidate the cautious read.
CoverageSource: ZeroHedge · Published here MON, AUG 17 · 10:25 AM ET · the only report in this recordHow this is decided →
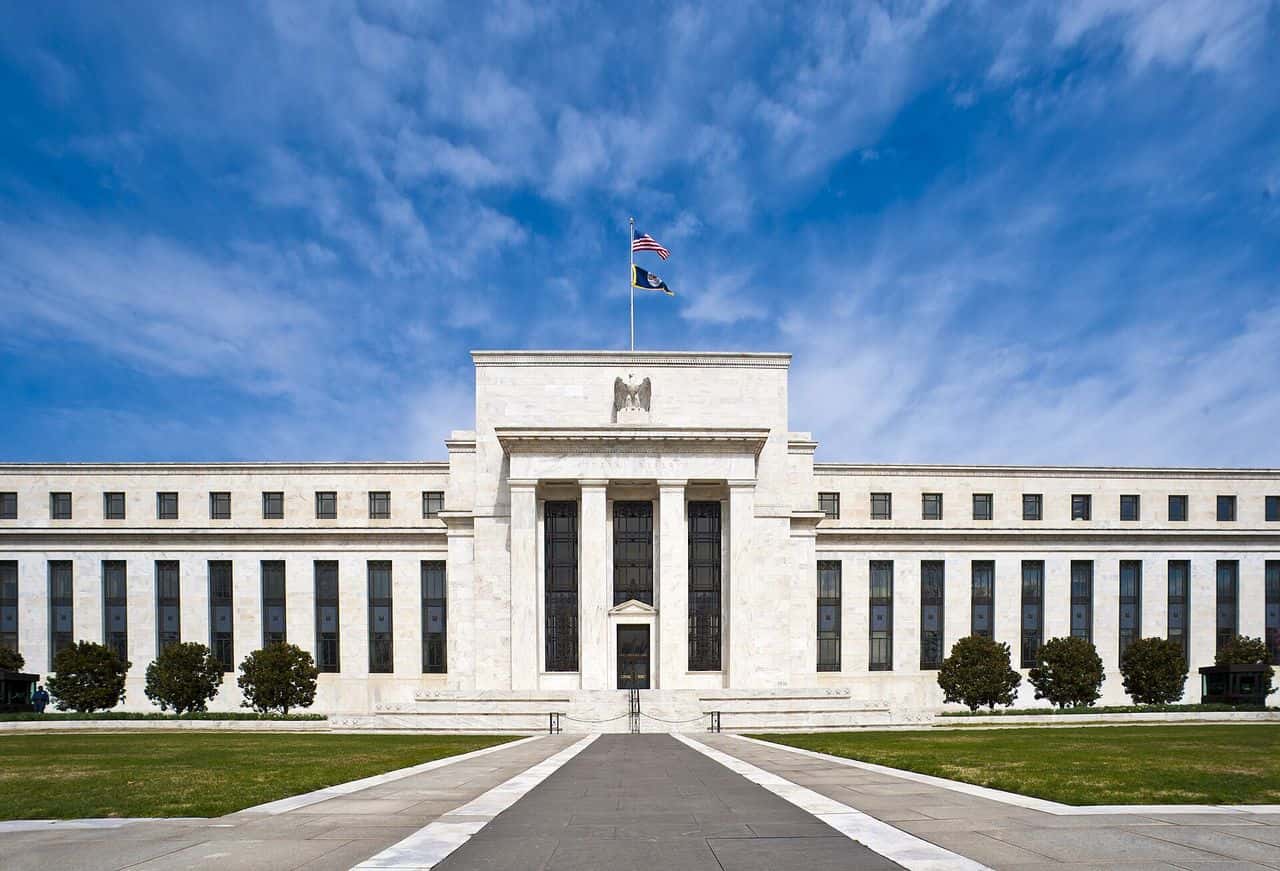 File photo · The Federal Reserve’s Eccles Building, Washington · Mar 2011 · Federal Reserve · Public domain · Source & license
Earlier context and later coverage are dated relative to this report. Automatically linked reports may cover a broader event.
No later reports linked yet.
Follow this story to find new evidence in your Following desk.
Price context does not establish that the story caused the move.
Home Depot’s $164.7B revenue base, 3.2% year-over-year growth and 33.3% gross margin provide a concrete earnings foundation if the company’s outlook remains resilient.
The bear case is primarily macro: higher long-term yields, elevated oil prices and fiscal-driven rate pressure could raise financing costs and weaken demand despite the company’s 8.6% net margin.
Kept as written · your side, if you take one, is graded privately against licensed closes after 10 trading days · nothing here is advice · How the Wire is made →