Qualcomm’s AWS Deal Takes Aim at Nvidia, But Comes With Fine Print
Qualcomm has struck an AWS deal that challenges Nvidia in AI infrastructure, but the arrangement includes limitations that temper the competitive threat. The setup is more consequential for Qualcomm’s diversification narrative than for Nvidia’s established scale and profitability.
Qualcomm's agreement with AWS targets Nvidia's position in AI infrastructure. The arrangement carries limitations that constrain its immediate competitive scope. Contract details including value, volumes, timing, and commercial restrictions remain undisclosed.
The deal arrives against sharply different company bases. Qualcomm's fiscal 2025 revenue was $44.3B, up 13.7% year over year, while Nvidia reported $215.9B of revenue for the fiscal year ended January 25, 2026, up 65.5%. Nvidia also reported a 71.1% gross margin and 55.6% net margin, underscoring the scale and economics Qualcomm would have to overcome in AI infrastructure.
For Qualcomm, the concrete link is strategic: AWS could provide a channel or validation point for expansion beyond its established businesses. For Nvidia, the mechanism is competitive rather than immediately financial; an AWS relationship with Qualcomm could support an alternative accelerator or platform, but no established revenue impact or displacement of Nvidia orders is evident.
The limiting side of the arrangement is central. The agreement carries fine print that constrains its commercial reach. Without disclosed contract economics or deployment milestones, the evidence supports a strategic signal rather than a quantified change to either company's earnings outlook.
The next useful markers are Qualcomm's and Nvidia's next earnings disclosures and any AWS announcement that clarifies deployment, customer availability, contract scope, or accelerator volumes. Until those details emerge, the deal is a narrative catalyst for Qualcomm and a longer-term competitive consideration for Nvidia, not an established earnings inflection.
The AWS deal supports QCOM’s AI-infrastructure expansion, but its undisclosed scope leaves NVDA’s scale advantage intact.
The immediate implication is strategic rather than an earnings reset: AWS validation could strengthen Qualcomm’s AI-infrastructure expansion, but the missing contract economics prevent a quantified read-through. Nvidia’s $215.9B revenue base and 71.1% gross margin leave the incumbent’s scale advantage intact until deployment and volume details appear.
The setup fails if the AWS arrangement is narrower than implied or if Qualcomm cannot convert it into disclosed deployments and revenue; the opposite risk is that AWS expands the relationship materially.
CoverageSource: Yahoo Finance · Published here FRI, SEP 11 · 11:40 AM ET · 4 reports · 1 publisher in this record · latest listed: Yahoo Finance · SUN, SEP 13 · 9:35 AM ETHow this is decided →
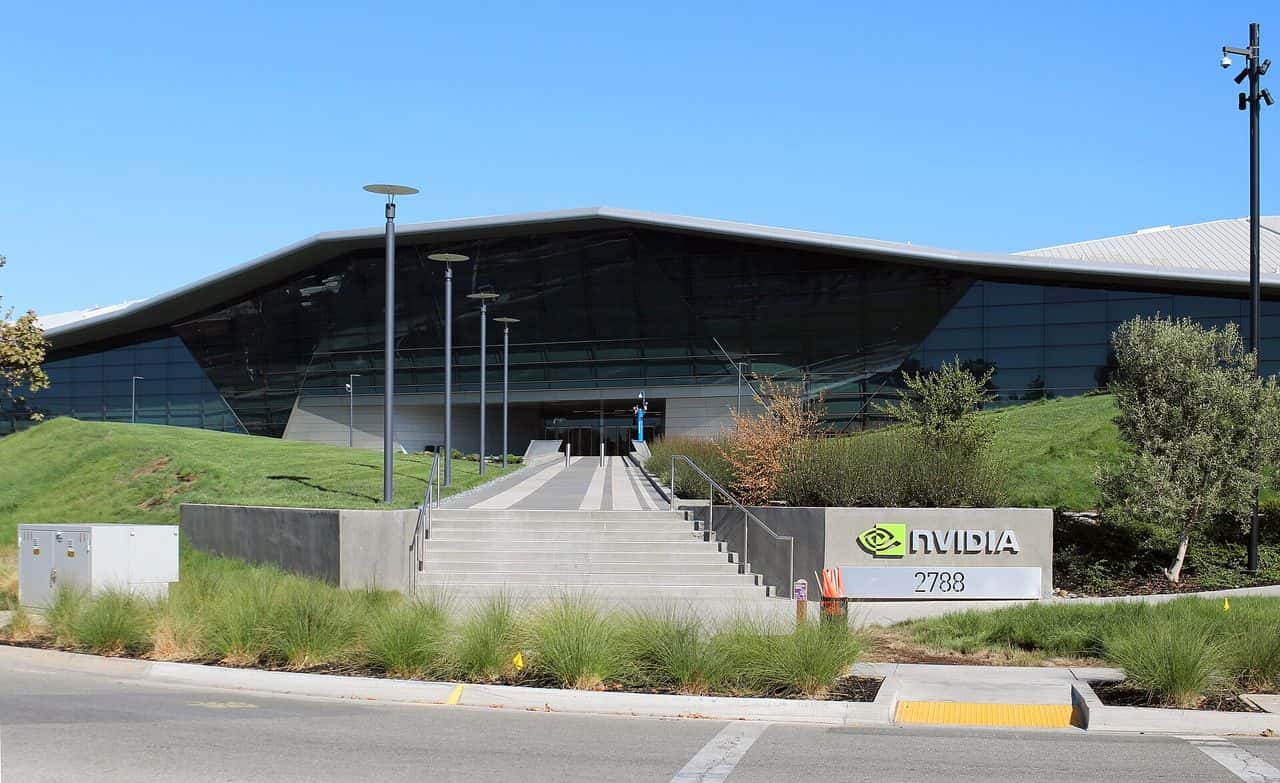 File photo · NVIDIA’s headquarters, Santa Clara · Aug 2018 · Coolcaesar · CC BY-SA 4.0 · Source & license
Earlier context and later coverage are dated relative to this report. Automatically linked reports may cover a broader event.
No later reports linked yet.
Follow this story to find new evidence in your Following desk.
Price context does not establish that the story caused the move.
Qualcomm’s $44.3B fiscal 2025 revenue base leaves room for an AWS-backed AI-infrastructure win to become a meaningful diversification channel.
The strongest opposing case is that the fine print reflects limited commercial scope, while Nvidia’s $215.9B revenue and 71.1% gross margin show the scale gap remains substantial.
Kept as written · your side, if you take one, is graded privately against licensed closes after 10 trading days · nothing here is advice · How the Wire is made →