After Market Losses, Nvidia Earnings Key; New Canada Tariffs
Nvidia’s upcoming earnings are in focus after market losses, while new Canada tariffs add another macro risk to semiconductor sentiment. With Nvidia generating $215.9B of revenue at a 55.6% net margin, the report is positioned to test whether exceptional AI demand can offset a more fragile risk backdrop.
Nvidia earnings represent the key near-term event, paired with newly announced Canada tariffs. This combination creates both company-specific execution risk and broader trade-policy uncertainty.
Nvidia's latest fiscal-year results show $215.9B in revenue, up 65.5% year over year, with a 71.1% gross margin, a 55.6% net margin and $4.90 diluted EPS. These figures establish a large and highly profitable business. The market will focus on Nvidia's earnings, its outlook for continued AI demand and any discussion of tariff exposure or supply-chain effects. The Canada tariffs could also matter through semiconductor sentiment and broader risk appetite.
NVDA’s exceptional growth and margins provide a fundamental cushion, but the earnings catalyst now carries downside sensitivity as market losses and new Canada tariffs raise the cost of a disappointment.
The setup is event-driven rather than a clean directional read: Nvidia's $215.9B revenue base, 65.5% YoY growth and 55.6% net margin support the fundamental case, while the market losses and new Canada tariffs increase sensitivity to guidance and policy commentary. The combination does not justify a single-name conviction target without additional clarity on consensus forecasts, valuation and tariff specifics.
A weaker earnings outlook or tariff-related supply-chain commentary could overwhelm the historical growth and margin profile.
CoverageSource: Investor's Business Daily · Published here SAT, AUG 22 · 11:47 AM ET · 2 reports · 1 publisher in this record · latest listed: Yahoo Finance · SAT, AUG 22 · 11:47 AM ETHow this is decided →
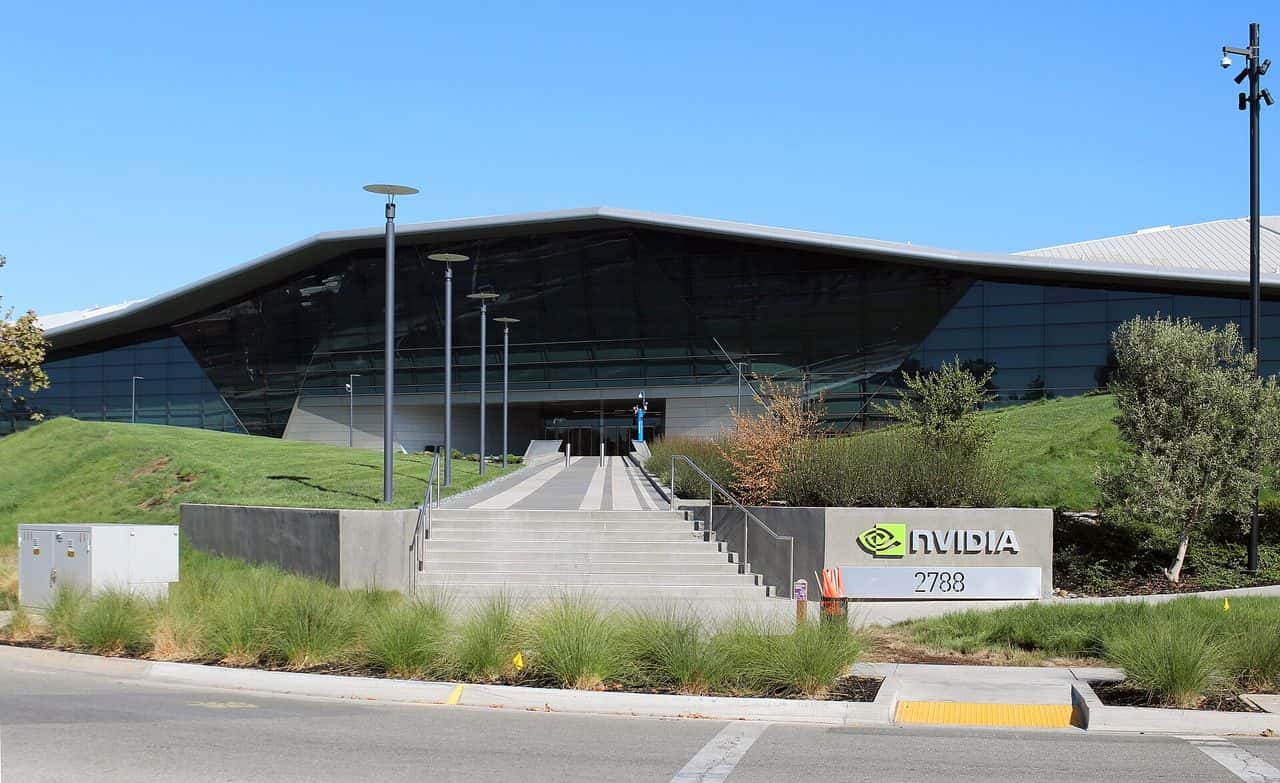 File photo · NVIDIA’s headquarters, Santa Clara · Aug 2018 · Coolcaesar · CC BY-SA 4.0 · Source & license
Earlier context and later coverage are dated relative to this report. Automatically linked reports may cover a broader event.
No later reports linked yet.
Follow this story to find new evidence in your Following desk.
Price context does not establish that the story caused the move.
The bull case rests on Nvidia’s $215.9B revenue, 65.5% YoY growth and 55.6% net margin, which show substantial operating momentum heading into earnings.
The bear case is that the earnings event arrives after market losses and alongside new Canada tariffs, while the available data provides no current guidance comparison to establish a margin of safety.
Kept as written · your side, if you take one, is graded privately against licensed closes after 10 trading days · nothing here is advice · How the Wire is made →