Nvidia becomes the bank of AI
Nvidia is working with Wall Street groups on a funding package of up to $500bn for AI infrastructure, positioning the chipmaker as a central financier as well as a supplier. The structure could expand demand for Nvidia systems, but it also ties future growth more closely to financing capacity and AI infrastructure credit risk.
Nvidia is working with Wall Street groups to assemble a $500bn funding package for AI infrastructure. The initiative would make the chipmaker a more central participant in financing the buildout around its own technology, rather than leaving capital formation entirely to customers and lenders.
The setup touches NVDA directly because financing can help customers fund additional data-center capacity and Nvidia systems. That matters against a business already reporting $215.9B of revenue, 65.5% YoY growth, 71.1% gross margins and 55.6% net margins for the cited fiscal period.
The bull case is that easier access to capital extends the AI infrastructure spending cycle and supports demand for Nvidia's high-margin products. The bear case is that the package concentrates exposure to customer credit quality, project economics and the durability of AI spending; details on terms, commitments or loss-sharing remain unclear.
The next read-through is the package's final size, structure and participants, along with evidence that funded projects translate into sustained orders rather than merely shifting financing around the ecosystem. Until those details emerge, the financing initiative is strategically positive but leaves the incremental risk profile unresolved.
The $500bn financing push broadens NVDA’s demand runway, but also moves more AI infrastructure and credit risk onto the chipmaker’s strategic perimeter.
The financing initiative could support further AI infrastructure orders, reinforcing NVDA’s already substantial operating momentum of $215.9B revenue and 65.5% YoY growth. The demand benefit cannot yet be separated from the added financing risk.
The setup weakens if the package lacks firm commitments, relies on stressed customers, or reveals that project economics and credit losses are being transferred toward Nvidia.
CoverageSource: Financial Times · Published here WED, AUG 12 · 2:36 PM ET · 3 reports · 3 publishers in this record · latest listed: MarketWatch · WED, AUG 12 · 2:36 PM ET (reaction)How this is decided →
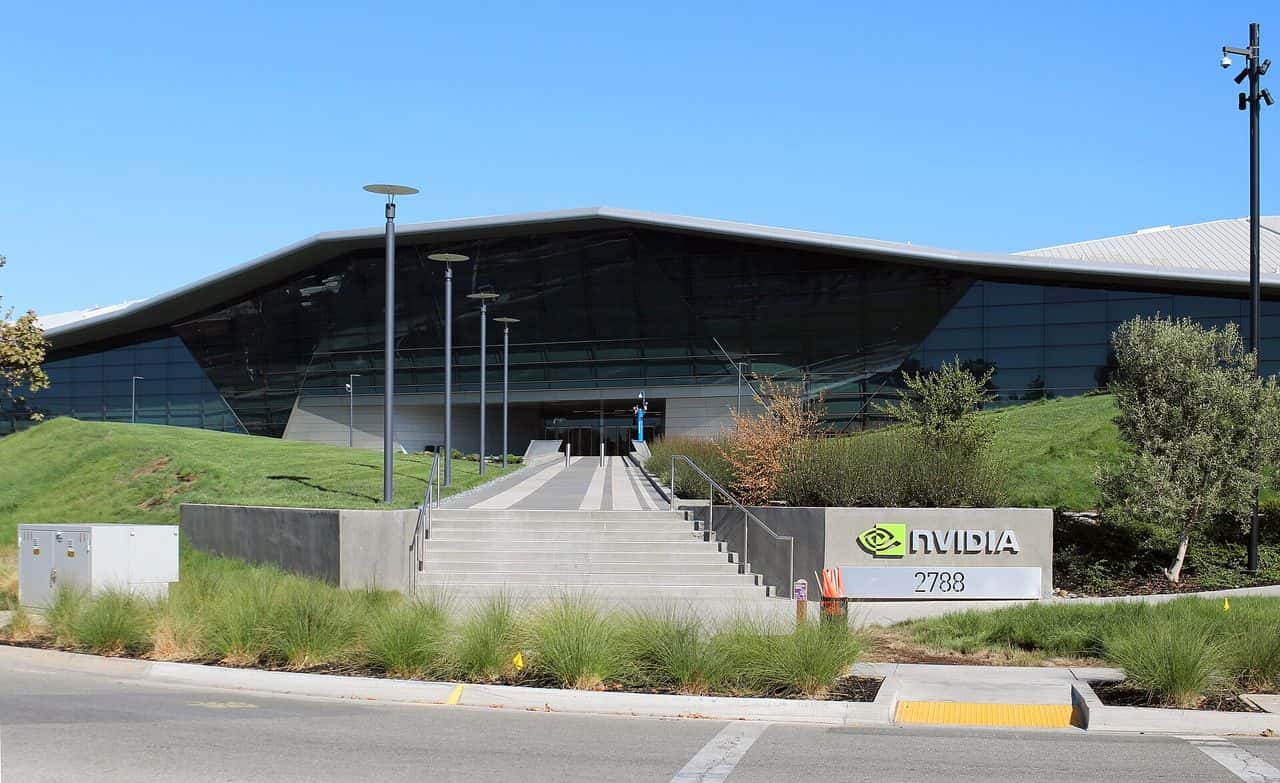 File photo · NVIDIA’s headquarters, Santa Clara · Aug 2018 · Coolcaesar · CC BY-SA 4.0 · Source & license
Earlier context and later coverage are dated relative to this report. Automatically linked reports may cover a broader event.
No later reports linked yet.
Follow this story to find new evidence in your Following desk.
Price context does not establish that the story caused the move.
A $500bn funding channel could extend the infrastructure cycle and support demand for NVDA systems while the company is already delivering 71.1% gross margins and 55.6% net margins.
The bear case is material but not yet quantified: without package terms, customer commitments or loss-sharing details, Nvidia could be helping finance an AI buildout whose credit and project risks are not yet visible.
Kept as written · your side, if you take one, is graded privately against licensed closes after 10 trading days · nothing here is advice · How the Wire is made →