Treasury signals potential expansion of debt buyback program to influence borrowing costs
The U.S. Treasury said it could expand its buybacks of outstanding debt as investors assess the effect on borrowing costs. The move creates a rates-market catalyst, but the direction for yields and risk assets remains unsettled without details on scale and execution.
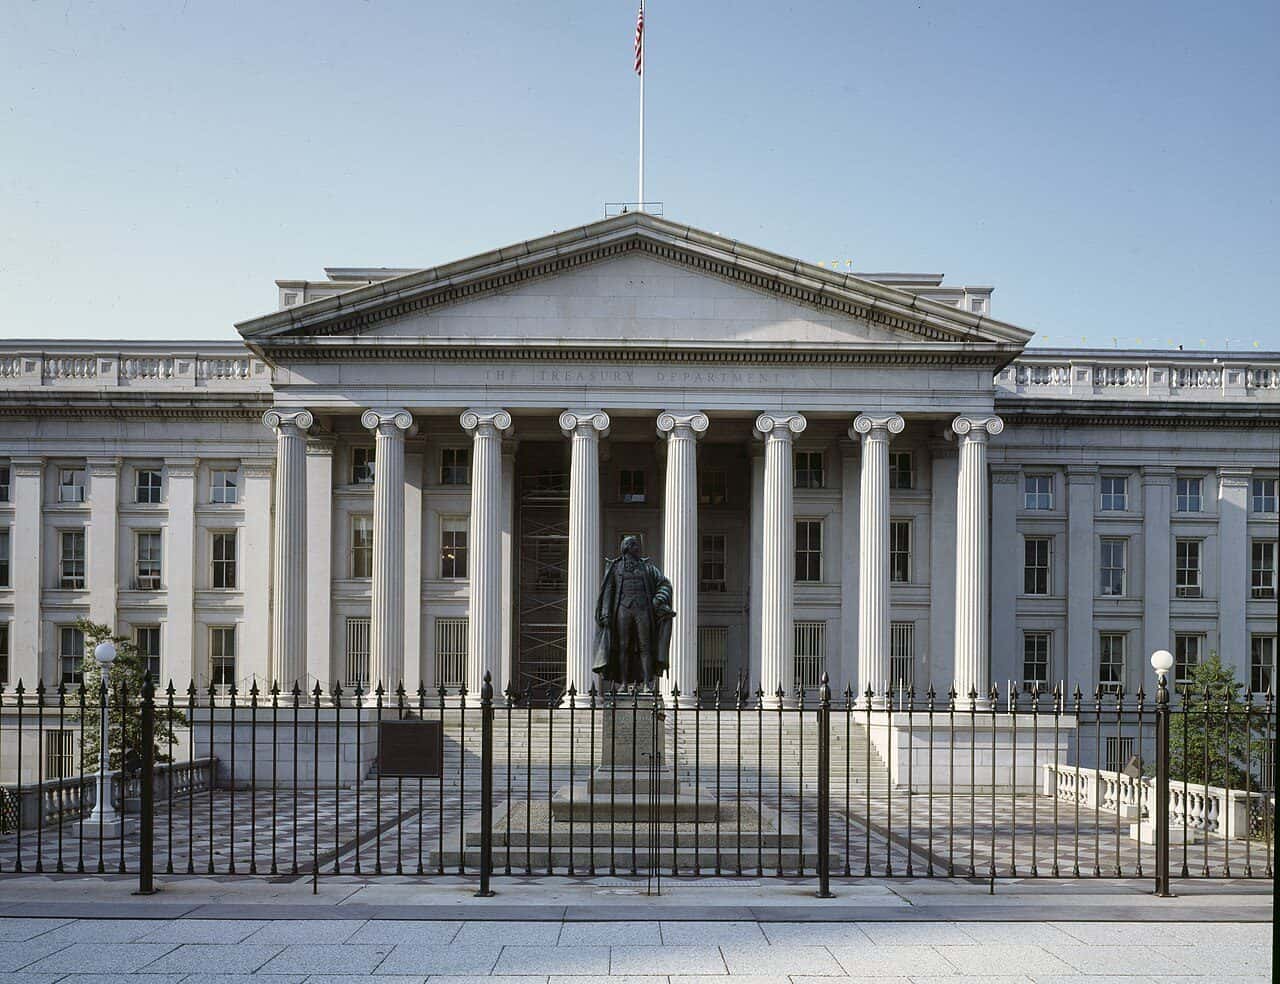 File photo · The US Treasury Building, Washington · date unknown · Carol M. Highsmith / Library of Congress · Public domain · Source & license
The story
The Treasury Department said it could begin to buy back more of its debt. Bond-market investors are assessing how the purchases could affect borrowing costs.
The mechanism runs through Treasury-market supply and liquidity: purchases of outstanding debt could alter the amount and composition of securities available to investors, with implications for pricing across the curve.
The key items to watch are the Treasury's formal details, the maturities targeted, the scale of any program, and the reaction in Treasury yields and funding markets. Until those parameters are disclosed, the macro read is a catalyst flag rather than a fully specified directional trade.
Our read · Wed, Aug 26
The Treasury buyback proposal puts rates, curve positioning and borrowing costs in play, but the evidence does not yet support a single-name equity read.
Why. The immediate consequence is a new policy-sensitive catalyst for Treasury pricing, with the potential effect depending on the size and maturity mix of purchases. No ticker enrichment or implementation detail is available, so the evidence supports monitoring the rates reaction rather than a defined equity direction.
Both cases
What could change this view: The trade thesis fails if Treasury does not expand buybacks or if the eventual program is too small to affect market supply and borrowing costs.
Who reported it · 2
Keep reading
Latest on the Wire
Anthropic debut fails to halt technology-led slide in US stocksUS MATCH Act puts ASML at center of China chip export disputeBeijing plans to bar young red-chip firms from overseas listingsGerman producer prices jump 8.1% in October as industrial inflation acceleratesChina seeks protections to restart US private-equity investmentsContinue on the Wire →Latest on the Wire
AMD shares fall 11% after Hunterbrook warns over China linksWalmart raises full-year outlook as e-commerce wins shoppersAnthropic IPO could become the largest in US history on ThursdayPIF Tower in Riyadh reportedly damaged in second Houthi attackContinue on the Wire →Top this week
Nvidia allies lobby board to bring back Jensen Huang as CEONvidia chair rules out Huang return as CEO after 75% sales outlookAnthropic Said to Guide IPO Pricing Above Market RangeNvidia interim CEO Colette Kress faces first earnings test after HuangBitcoin nears $64,000 as Anthropic IPO lifts Nasdaq futures nearly 2%About this report
Reported by NYT Business as What’s Behind the U.S. Treasury’s Latest Attempt to Lower Interest Rates
, . Who answers for this
2 reports from 2 publishers in this record. Closes are licensed end-of-day data from Databento; the move after a story is its first close against the close before it. How this is decided →
Kept as written · your side, if you take one, is graded privately against licensed closes after 10 trading days · nothing here is advice · How the Wire is made →