Z.AI Claims New Model Taking on Anthropic, OpenAI | The China Show
Chinese startup Z.AI says it has built the Ox Alpha stealth model, positioning a new entrant against Anthropic and OpenAI as Nvidia says AI-driven sales growth could continue through 2028. The setup keeps model competition as a potential swing factor for AI demand, but the available evidence points more directly to Nvidia’s current revenue and margin execution than to an immediate change in its earnings trajectory.
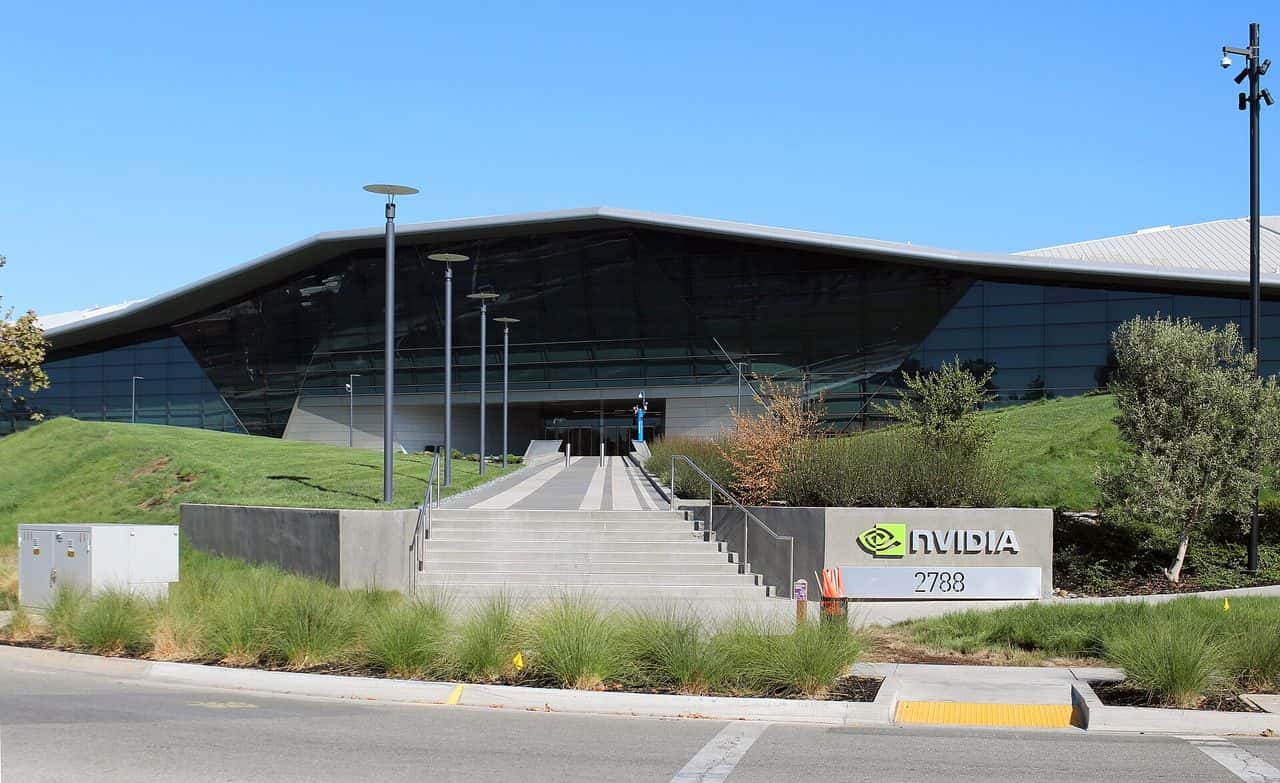 File photo · NVIDIA’s headquarters, Santa Clara · Aug 2018 · Coolcaesar · CC BY-SA 4.0 · Source & license
Z.AI built a model called Ox Alpha that is positioned as a competitor to Anthropic and OpenAI. The system is described as a stealth model entering a field dominated in global investor attention by US model providers.
The announcement came alongside developments involving Shein and its Hong Kong IPO near the middle of its guided range, and Nvidia's statement that AI-fueled sales growth could extend to 2028. These developments reflect broader movements in China technology, capital markets and the continuing buildout of AI infrastructure.
Nvidia is a major player in this space with significant scale and profitability. Its fiscal-year revenue was $215.9B, up 65.5% YoY, with a 71.1% gross margin, a 55.6% net margin and $4.90 diluted EPS for the fiscal year ended 2026-01-25. Any new model ecosystem would need to affect this existing scale before it could translate into a direct change to Nvidia's reported results.
Ox Alpha's quality, cost, adoption and safety remain unestablished relative to Anthropic or OpenAI. The model is not connected to a specific chip order or Nvidia customer. Nvidia's statement about sales continuing to benefit from AI through 2028 is a company assertion rather than an independent forecast.
Key evidence going forward would include a public technical evaluation of Ox Alpha, details of its release and signs of customer or developer adoption. For Nvidia, important checks are subsequent revenue, margin and EPS disclosures against the $215.9B, 71.1%, 55.6% and $4.90 baseline, as well as any company commentary that changes the expected duration of AI-fueled demand.
The Z.AI model claim adds competitive noise, but NVDA’s $215.9B revenue base and 71.1% gross margin keep the immediate read anchored to execution rather than a demonstrated demand shock.
Nvidia’s $215.9B revenue, 71.1% gross margin and 55.6% net margin provide a substantial operating base, while the company’s claim that AI-fueled sales growth can extend to 2028 keeps the demand case active but does not resolve the competitive question.
A credible Ox Alpha benchmark, rapid adoption or evidence of lower-cost AI deployment changing accelerator demand would make the model claim more material to NVDA; alternatively, weaker Nvidia revenue or margins in the next print would undercut the execution case.
CoverageSource: Bloomberg Television · Published here THU, AUG 27 · 1:08 AM ET · the only report in this recordHow this is decided →
Earlier context and later coverage are dated relative to this report. Automatically linked reports may cover a broader event.
Earlier context
- · Investing.com · Arc starting point
Nvidia scales back $250 billion OpenAI data center guarantee, WSJ reports
- · Investing.com · Automatically linked
Nvidia to provide up to $105 billion guarantee for OpenAI’s Ohio data center
- · PR Newswire · Automatically linked
- · Yahoo Finance UK · Automatically linked
- · Yahoo Finance · Automatically linked
SpaceX Rises 3% as Musk Pulls the NVIDIA Orbital Data Center Into 2027, JPMorgan Sees 75% Upside
- · Investing.com · Automatically linked
Wall St futures steady after weekly losses; Nvidia results, Jackson Hole in focus
- · MarketWatch · Automatically linked
- · Benzinga · Automatically linked
- · Financial Times · Automatically linked
Coverage after this report
- · Bloomberg Television · Automatically linked
Putin Moves to Escalate War in Ukraine, Nvidia Fuels Faith in AI Boom
- · Investing.com · Automatically linked
S&P 500: Nvidia’s Earnings and Fed Outlook Could Determine the Next Move
- · Investing.com · Automatically linked
Nvidia’s $279 billion memory commitment reshapes the semiconductor competitive landscape
- · Investing.com · Automatically linked
U.S. stock futures fall as investors await PCE inflation, Nvidia results
- · Bloomberg Television · Automatically linked
China Defiant Over Iran Ties; Tech Stocks in Focus Before Nvidia Results
- · Yahoo Finance · Automatically linked
Nvidia pauses revenue-sharing deals with AI cloud companies, WSJ reports
- · Bloomberg Television · Automatically linked
- · GlobeNewswire · Automatically linked
NVIDIA Announces Financial Results for Second Quarter Fiscal 2027
- · Investing.com · Automatically linked
Anthropic signs $35 billion cloud deal with Nvidia-backed Lambda, WSJ reports
- · GlobeNewswire · Automatically linked
NVIDIA Expands AI Infrastructure Capacity in Partnership With Australia’s Data Center Ecosystem
Follow this story to find new evidence in your Following desk.
Price context does not establish that the story caused the move.
Nvidia’s stated view that AI-fueled sales growth can extend to 2028, alongside $215.9B of revenue and a 71.1% gross margin, supports the case that new model launches continue expanding rather than immediately displacing infrastructure demand.
The bear case is presently limited to the unverified possibility that a capable, lower-cost Chinese model such as Ox Alpha could reduce the compute required per unit of AI output or intensify pricing pressure, with no benchmark or customer evidence supplied.
Kept as written · your side, if you take one, is graded privately against licensed closes after 10 trading days · nothing here is advice · How the Wire is made →