Antitrust attacks start to bite into Apple’s $100bn services business
Antitrust rulings and new App Store rules are beginning to pressure Apple’s roughly $100bn services business, one of its most profitable growth engines. The setup shifts a key part of the AAPL thesis toward regulatory pressure on monetization and margins rather than iPhone demand alone.
Court decisions and changes to App Store rules are starting to affect the economics of Apple's services business. The business is roughly $100bn and has been an important source of profitable growth for the iPhone maker.
The regulatory pressure is centered on the App Store, linking Apple's rules and commission structure to the broader antitrust cases. That makes the issue relevant to the services segment rather than only to Apple's hardware sales.
Apple reported FY2025 revenue of $416.2B, up 6.4% YoY, with a 46.9% gross margin and a 26.9% net margin. The key evidence ahead is how future rulings and App Store changes affect services growth, monetization and consolidated margins.
The antitrust rulings move the risk to the downside for AAPL by putting pressure on the monetization and margins of its roughly $100bn services engine.
The immediate consequence is greater uncertainty around a high-margin growth engine: App Store rule changes can pressure services monetization even while Apple’s FY2025 business remained large and profitable, with $416.2B of revenue and a 46.9% gross margin. The bear case is stronger than the bull case because the supplied reporting identifies an active regulatory mechanism, but the lack of a quantified earnings impact argues for a measured move rather than an aggressive target.
The trade fails if subsequent Apple disclosures show no material effect on services growth, monetization or margins, or if court and App Store changes are narrowed.
CoverageSource: Financial Times · Published here TUE, AUG 18 · 12:00 AM ET · the only report in this recordHow this is decided →
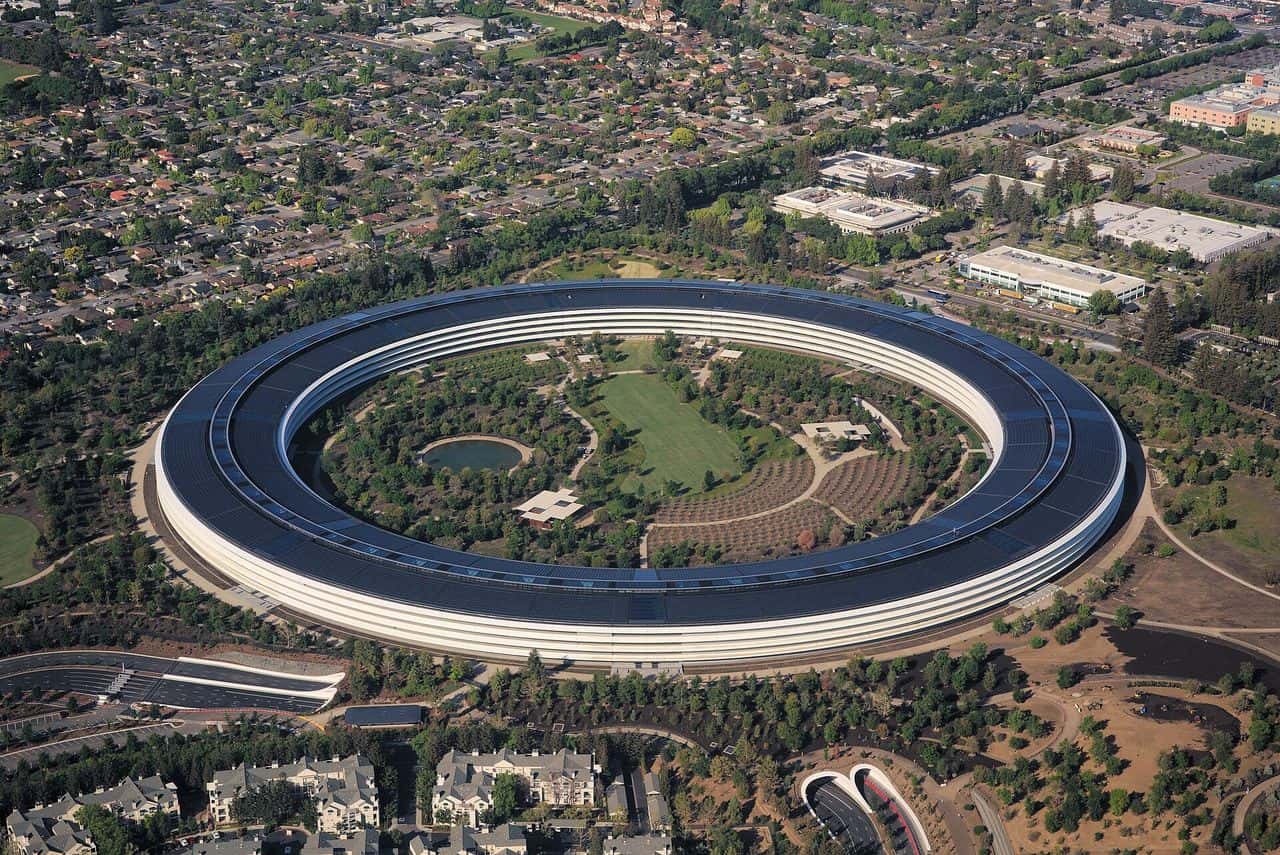 File photo · Apple Park, Cupertino · Apr 2018 · Daniel L. Lu (dllu) · CC BY-SA 4.0 · Source & license
Earlier context and later coverage are dated relative to this report. Automatically linked reports may cover a broader event.
No later reports linked yet.
Follow this story to find new evidence in your Following desk.
Price context does not establish that the story caused the move.
Apple’s FY2025 scale—$416.2B of revenue, a 26.9% net margin and $7.46 diluted EPS—could absorb an initially limited App Store impact while its broader ecosystem continues to support services.
The concrete bear hook is that court rulings and new App Store rules are already beginning to weigh on the roughly $100bn services business, putting pressure on a profitable growth engine.
Kept as written · your side, if you take one, is graded privately against licensed closes after 10 trading days · nothing here is advice · How the Wire is made →