A China Chip Denial Lands Before Nvidia’s (NVDA) Big Week
A China chip denial has landed ahead of Nvidia’s upcoming results week, putting geopolitical and demand questions back in focus for NVDA. Nvidia’s latest fiscal-year profile remains exceptionally strong.
Nvidia's upcoming results week comes amid a denial involving China's chip market. Nvidia reported fiscal-year revenue of $215.9B, up 65.5% YoY, with a 71.1% gross margin and a 55.6% net margin, according to SEC EDGAR data. Those figures establish a strong operating backdrop, but the impact of China-related developments on the company's next quarter and forward outlook remains unclear. Key drivers for investors include Nvidia's results and guidance, along with any company disclosure on China demand, export restrictions, or customer access. Without clarity on the denial's quantified impact, the situation creates a catalyst and risk frame rather than a firm earnings-direction signal.
The China denial adds headline risk ahead of NVDA’s results, but its revenue, margins, and earnings profile leave the evidence mixed rather than directional.
The immediate setup is event risk without a quantified fundamental impairment: Nvidia’s reported $215.9B revenue, 65.5% YoY growth, 71.1% gross margin, and 55.6% net margin provide a strong base, while the China denial has no stated impact on guidance or demand. The next earnings disclosure must establish whether China is merely a headline overhang or a material constraint on the outlook.
A weaker-than-expected outlook or explicit disclosure of China demand and export-control pressure would invalidate the balanced read.
CoverageSource: Yahoo Finance · Published here FRI, AUG 21 · 4:21 AM ET · the only report in this recordHow this is decided →
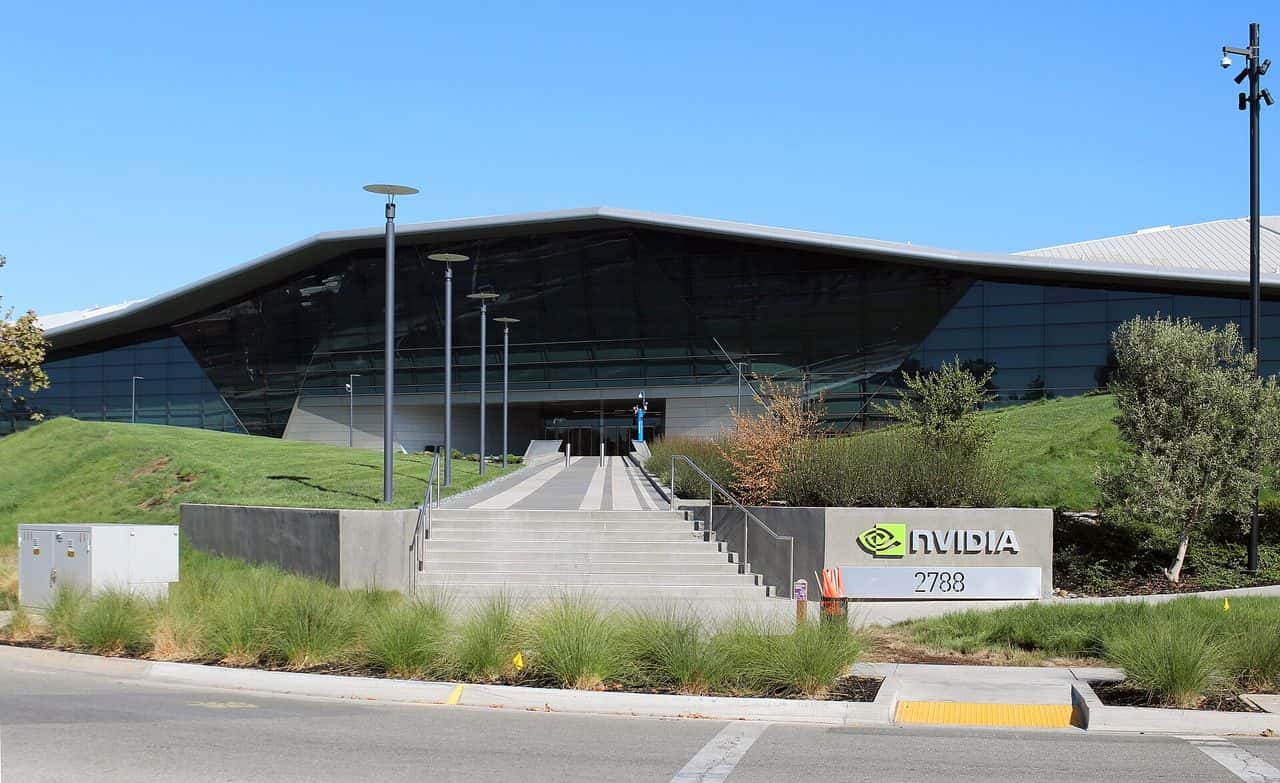 File photo · NVIDIA’s headquarters, Santa Clara · Aug 2018 · Coolcaesar · CC BY-SA 4.0 · Source & license
Earlier context and later coverage are dated relative to this report. Automatically linked reports may cover a broader event.
No later reports linked yet.
Follow this story to find new evidence in your Following desk.
Price context does not establish that the story caused the move.
Nvidia’s $215.9B revenue and 65.5% YoY growth, alongside a 71.1% gross margin and 55.6% net margin, provide a concrete operating base against an unquantified China headline.
The denial lands immediately before results and could expose an unquantified China or regulatory risk that the available fiscal-year figures do not capture; the evidence is too thin for a stronger bear case.
Kept as written · your side, if you take one, is graded privately against licensed closes after 10 trading days · nothing here is advice · How the Wire is made →