The Pulse with Francine Lacqua 8/26/2026
Trade tensions with Canada are escalating as the Trump administration discusses additional penalties after Mark Carney announced dollar-for-dollar retaliation, while markets await Nvidia earnings and the Federal Reserve’s preferred inflation gauge. For NVDA, the setup pairs a powerful operating base with a near-term binary catalyst and broader risk aversion.
The Trump administration is discussing additional trade penalties against Canada after Canadian Prime Minister Mark Carney unveiled dollar-for-dollar retaliation to new US tariffs imposed on Saturday.
US stocks struggled for direction and Treasuries slipped as traders reduced risk ahead of Nvidia's earnings and July's reading of the Federal Reserve's preferred inflation gauge. Nvidia's FY 2026 revenue is $215.9B, up 65.5% year over year, with a 71.1% gross margin and a 55.6% net margin.
The trade-policy dispute adds a macro risk channel for semiconductor demand and market sentiment. ECB Executive Board member Isabel Schnabel argued that interest rates must rise further as the Middle East conflict and stronger euro-area conditions complicate the policy outlook.
The next decisive information is Nvidia's earnings report and the accompanying outlook. Details on trade penalties, the scope of any Canadian retaliation, and the July inflation reading will determine whether the macro backdrop remains a secondary risk or becomes a larger driver of the shares.
NVDA’s $215.9B revenue base and 65.5% growth support the bull case, but the immediate risk is a binary earnings read against tariff and rates uncertainty.
The setup is dominated by the imminent earnings catalyst rather than by the Canada trade headline alone. Nvidia enters that event with a substantial operating cushion—$215.9B of revenue, 65.5% year-over-year growth, and 55.6% net margins—but tariff escalation and a potentially less supportive rates backdrop raise the cost of a disappointing outlook.
A weaker-than-expected Nvidia outlook, alongside broader risk aversion from tariff escalation or a hotter July inflation reading, would undermine the constructive operating evidence.
CoverageSource: Bloomberg Television · Published here WED, AUG 26 · 7:43 AM ET · the only report in this recordHow this is decided →
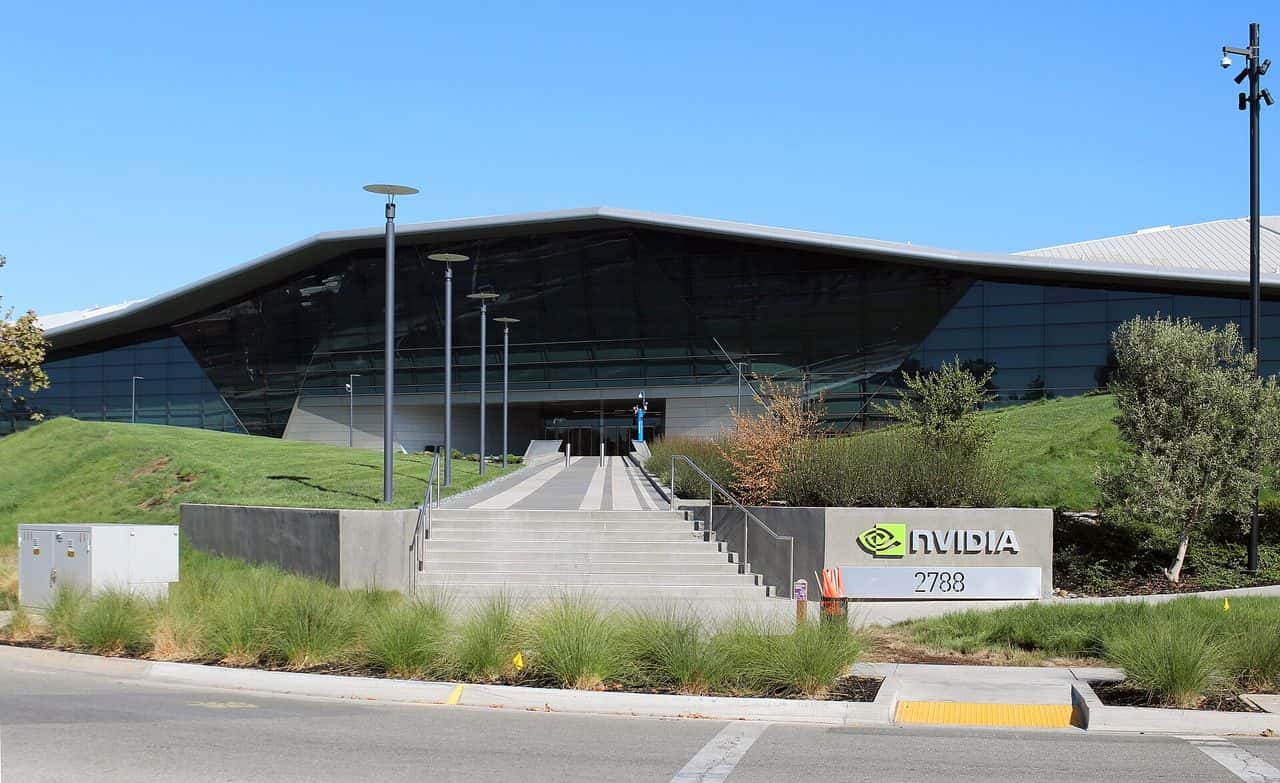 File photo · NVIDIA’s headquarters, Santa Clara · Aug 2018 · Coolcaesar · CC BY-SA 4.0 · Source & license
Earlier context and later coverage are dated relative to this report. Automatically linked reports may cover a broader event.
No later reports linked yet.
Follow this story to find new evidence in your Following desk.
Price context does not establish that the story caused the move.
Nvidia’s $215.9B revenue and 65.5% year-over-year growth, backed by a 71.1% gross margin and 55.6% net margin, provide a strong fundamental base into earnings.
The bear case is event-driven: additional trade penalties, tighter-rate expectations after Schnabel’s comments, or a weaker Nvidia outlook could overwhelm the company’s otherwise strong reported operating profile.
Kept as written · your side, if you take one, is graded privately against licensed closes after 10 trading days · nothing here is advice · How the Wire is made →